Jamie Dimon Fires Warning Shot in Stablecoin Battle
The fight between Wall Street and the crypto industry just escalated.
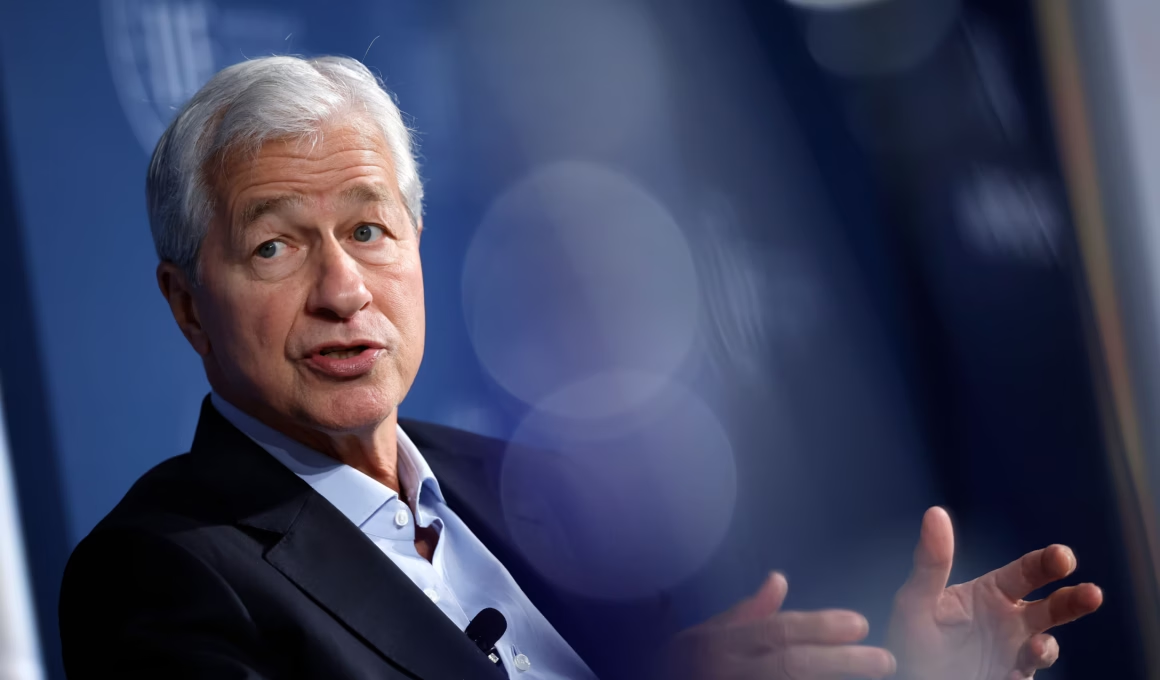
Jamie Dimon, CEO of JPMorgan Chase, delivered a blunt message this week: if crypto companies want to offer rewards on stablecoins, they should become banks.
His comments come at a crucial moment in Washington, where negotiations between banking leaders, crypto executives, and the White House have stalled over a key issue—whether crypto firms should be allowed to pay customers yield on stablecoin holdings.
That disagreement has effectively frozen one of the crypto industry’s most important legislative goals: a comprehensive market structure bill.
What Is the Fight About?
Understanding Stablecoins and Rewards
Stablecoins are digital tokens pegged to the value of the U.S. dollar. They are designed to maintain a steady value, unlike volatile cryptocurrencies such as Bitcoin.
Some crypto platforms, including major exchanges like Coinbase, allow customers to earn rewards or yield for holding stablecoins on their platforms. In simple terms, users deposit their stablecoins and receive interest-like returns.
That’s where the problem begins.
Banks argue that if crypto firms can offer attractive yields without being subject to the same rules banks must follow, it creates an uneven playing field—and potentially serious financial risk.
Jamie Dimon’s Hardline Position
“If You Want to Be a Bank, Become a Bank”
In a recent interview with CNBC, Dimon didn’t mince words.
He argued that banks operate under strict regulations, including federal deposit insurance, anti-money laundering standards, reporting requirements, transparency rules, and community investment obligations.
Crypto companies offering stablecoin rewards, he said, are not subject to the same regulatory burden.
“It can’t be: You have these people doing one thing without any regulation, and these people doing another,” Dimon said. “If you do that, the public will pay. It will get bad.”
His message was clear: if crypto firms want to offer bank-like services such as yield on deposits, they should follow bank laws.
Dimon, who has long been skeptical of Bitcoin and parts of the crypto ecosystem, framed his argument around financial stability. According to him, regulation exists for a reason—to protect the public and ensure a safe financial system.
Why Banks Are Concerned
Competition for Deposits
Traditional banks rely heavily on customer deposits. These deposits fund lending activities and help maintain liquidity.
If crypto platforms offer significantly higher yields on stablecoins, customers may move their money away from low-yield savings accounts into digital wallets. That shift could weaken banks’ deposit bases.
From the banking industry’s perspective, allowing crypto companies to offer high-yield programs without similar regulatory oversight is unfair and potentially destabilizing.
Banks argue that they must comply with:
- Federal deposit insurance programs
- Strict anti-money laundering rules
- Capital and liquidity requirements
- Community investment obligations
- Detailed reporting and governance standards
Crypto companies, they say, are not held to the same level of scrutiny.
The Stalled Crypto Market Structure Bill
Why the Legislation Matters
The broader crypto market structure bill is highly anticipated within the digital asset industry. It aims to clarify how cryptocurrencies are regulated in the United States, define the roles of different regulators, and provide clearer rules for companies operating in the space.
The bill was expected to move forward in January and even appeared poised for a vote in the powerful Senate Banking Committee.
But just before the vote, Coinbase reportedly withdrew its support for the legislation.
The reason? Proposed amendments that would restrict or limit stablecoin reward programs.
The vote was quickly tabled—and it hasn’t been rescheduled since.
The Role of the GENIUS Act
Last summer, President Donald Trump signed the stablecoin-focused GENIUS Act into law.
Under the GENIUS Act, stablecoin issuers must comply with specific requirements related to anti-money laundering, liquidity, and risk management.
However, the current dispute isn’t primarily about stablecoin issuers. It centers on middlemen like Coinbase, which want to ensure that their ability to pass rewards to customers remains intact in future legislation.
A separate proposed rulemaking from the Office of the Comptroller of the Currency recently outlined how the GENIUS Act would be implemented. Industry observers are divided over whether those rules could indirectly affect stablecoin reward programs.
But the bigger battle remains within the market structure bill.
White House Efforts to Broker a Deal
Meetings Without Results
Recognizing the urgency of the situation, the White House has hosted multiple meetings between banking executives and crypto leaders in an attempt to reach a compromise.
Initially, there was pressure to finalize a deal by March 1. Lawmakers are aware that Congress slows down significantly ahead of midterm elections, which are approaching in November.
If an agreement isn’t reached soon, the bill could be delayed indefinitely.
So far, however, the talks have produced few concrete results.
Banking-side negotiators reportedly believe that a compromise may not be achievable in time. Crypto leaders have pushed back on that view, but Dimon’s recent statements suggest the divide remains wide.
Why This Standoff Matters
A Question of Regulation vs Innovation
At its core, the debate reflects a larger philosophical divide.
Crypto companies argue that innovation should not be stifled by excessive regulation. They believe stablecoin rewards are simply a modern financial product that benefits consumers.
Banks counter that offering yield without bank-level safeguards introduces systemic risk.
The tension mirrors earlier battles in financial history, where new technologies challenged established institutions.
Potential Economic Impact
Dimon warned that unequal regulation could eventually harm the public.
His concern is that if crypto firms operate without sufficient oversight while offering bank-like services, a crisis could emerge—one that might require government intervention.
Supporters of crypto, on the other hand, argue that overregulation could push innovation offshore and weaken America’s position in digital finance.
The Clock Is Ticking
With midterm elections approaching, time is running short.
If lawmakers fail to resolve the stablecoin rewards issue, the broader crypto market structure bill may remain stuck in limbo.
For crypto companies, the stakes are high. Clear federal rules would provide regulatory certainty and potentially attract institutional investment.
For banks, the stakes are equally significant. They want to ensure that any competitor offering similar financial services plays by comparable rules.
What Happens Next?
Several outcomes are possible:
- Congress could amend the bill to limit stablecoin reward programs.
- A compromise could emerge that imposes additional safeguards on crypto platforms offering yield.
- The legislation could stall entirely, pushing major decisions into the next congressional session.
For now, the impasse continues.
Dimon’s comments have reinforced the seriousness of the divide, and neither side appears ready to back down easily.
Final Thoughts
The battle over stablecoin rewards is more than just a niche policy debate. It represents a defining moment in the relationship between traditional banking and the crypto industry.
Jamie Dimon’s message was straightforward: if crypto firms want to act like banks, they should be regulated like banks.
Whether lawmakers agree—or side with crypto innovators—will shape the future of digital finance in the United States.
As negotiations drag on and the legislative calendar tightens, the outcome of this standoff could determine not only the fate of a single bill, but the broader direction of the American financial system.